

 Back
We’ll often see headlines quoting how many gigawatts of new solar farms or coal plants China is building. But it’s hard to get a meaningful sense of scale for how electricity generation in China is changing.
The chart puts it in perspective.

In 2025 alone, China’s electricity generation increased by almost 500 terawatt-hours (TWh). This is compared here to the total amount of electricity that whole countries generate each year.
Germany generates almost exactly that amount. That means China effectively added a Germany-sized grid to its electricity system in just one year.
What’s also quite staggering is that almost all of this new generation came from solar and wind. China generated 340 TWh more electricity from solar than the year before.
That’s more than our two home countries, the UK and Spain, generate from all sources each year.
Low-carbon sources grew so much that coal power in China actually fell slightly.
European drivers are escaping high gas prices and buying more cheap Chinese EVs. In the U.S., that’s impossible.
This analysis and news roundup come from the Canary Media Weekly newsletter. Sign up to get it every Friday.
As the war in Iran spikes gasoline prices around the globe, drivers in many countries have headed for an obvious emergency exit: EVs. But buyers in the U.S. aren’t following suit, and a lack of affordable EV options is a big reason why.
While global EV sales plunged in January and February from 2025’s record heights, they rebounded in March and April, according to data out this week from Benchmark Mineral Intelligence. That’s largely thanks to a surge in Europe, where EV sales were 27% higher this April than the same month last year. Rising gasoline prices fueled the region’s market, BMI says, as did the increasing availability of cheap Chinese EV imports.
The latter is exactly what the U.S. lacks. While used EVs are now cost-competitive with used gas cars, that’s not the case for new models. The cheapest new EV sold in the U.S., the Nissan Leaf, starts at just under $30,000. But in China, dozens of EVs retail for around $25,000 or less, including several models from BYD, which surpassed Tesla as the world’s top EV seller earlier this year. And while the Asian superpower has ramped up exports to Europe, Latin America, and, more recently, Canada, its cars face a 100% tariff and national security rules in the U.S. that make them impossible to sell.
It’s not that U.S. drivers aren’t interested in electrifying their ride. Shopping sites Cars.com and CarGurus both say searches for EVs have jumped since the Iran war began. And a February survey from Cox Automotive found nearly half of Americans considering an EV would pick the Chinese-made Geely Xingyuan over a Tesla Model Y, while 38% would select BYD’s Seagull over the Tesla.
But letting Chinese EVs into the U.S. is a scary prospect for domestic automakers. The American EV sector is only just finding its sea legs, having been knocked back time and time again by tariffs, politics, and the federal tax credit rollback. It’s probably not reassuring that President Donald Trump has said he’s open to Chinese investment in the U.S., provided companies use American labor — and that Trump’s meetings this week with Chinese President Xi Jinping similarly indicated a softening in relations.
“[U.S. automakers are] absolutely more than worried — they’re scared stiff,” Michael Dunne, chief executive officer of automotive consultancy Dunne Insights, told Politico. “Imagine if the Chinese come in with a $25,000 EV. That could catch like wildfire.”
For now, though, BYD in the USA remains miles down the road — if it’s a destination we ever reach at all.
On wind and solar, Interior won’t go down without a fight
Interior Secretary Doug Burgum on Wednesday affirmed that the Trump administration will appeal a ruling that struck down Interior Department policies stymieing wind and solar permitting.
Last month, a federal judge ordered the administration to stop enforcing five actions that effectively blocked all wind and solar energy permitting on public land, including a policy that required Burgum to personally sign off on projects that need federal permissions. The blockade was “arbitrary and capricious,” the judge said, especially considering permitting for fossil fuel companies marched on as usual.
Congress has been trying for years to enact bipartisan legislation to reform energy permitting, but Trump’s anti-renewables crusade has led Democrats to repeatedly back out. This appeal is likely to derail reform attempts once again, as two senators said last month they’d cooperate only if the Interior Department lets solar and wind projects keep rolling.
Geothermal innovation keeps heating up
This week marked a milestone for the geothermal industry — a potentially key piece of the push to secure clean, 24/7 power.
On Wednesday, Fervo Energy became the first next-generation geothermal company to go public, bringing in $1.9 billion from its IPO and securing a valuation of about $7.7 billion, Canary Media’s Dan McCarthy reports. While traditional geothermal energy production has been limited to certain geologic areas, like volcanic regions, Fervo is borrowing drilling techniques from the fossil fuel industry to access deep-down heat in more locations.
Another thing geothermal may be able to borrow from oil and gas drillers? Their abandoned wells. The U.S. is littered with these sites, many of which have no clear owner and are polluting the air and groundwater, Canary’s Maria Gallucci reports. A growing number of both Republican- and Democratic-led states are exploring whether these wells could be repurposed for geothermal energy production — a complicated task with huge potential upside.
Fossil fuels all the way down: In rural Jasper County, Indiana, residents are fighting to shut down a 50-year-old coal plant running past its prime, while also staring down another polluting prospect: a new gas plant to power a data center. (Canary Media)
Tapping the brakes: President Donald Trump says he supports suspending the federal gas tax, though even Republicans in Congress are reluctant to move on his call to action. (Politico)
Clean power climbs: A new dashboard that tracks national and state-level progress on deploying clean energy finds that the U.S. produced nearly three times as much solar, wind, and geothermal power in 2025 as it did in 2016. (Environment America, news release)
Generating controversy: Elon Musk–led company xAI has installed dozens of “temporary-mobile” gas turbines in Mississippi to power its data centers, which remain exempt from state oversight even as neighboring residents push back over pollution and noise concerns. (Mississippi Today)
Inside offshore wind communities: After months spent interviewing residents in three offshore wind hubs in Connecticut, Maryland, and Massachusetts, researchers find that communities are excited by the projects’ economic promise but are unsure it’ll last once construction is finished. (NBC Connecticut)
Georgia’s nuclear warning: Utility customers are still paying the cost of Georgia Power’s addition of nuclear reactors to Plant Vogtle, which ran seven years behind schedule and more than two and a half times over budget, providing a cautionary tale for advocates of the energy source. (Inside Climate News)
Mercury rising: Coal power plants released 9% more mercury in 2025 than they did a year earlier — a number that will likely grow as the Trump administration looks to expand coal power generation and loosen regulations that could curb the toxic pollutant. (New York Times)
A total of 112 gigawatts of batteries were deployed around the world in 2025 — 10 times the amount added just four years prior.
See more from Canary Media’s “Chart of the Week” column.
First came the solar. Now, the batteries have arrived.

Installations of grid batteries, which can store solar and other energy for later use, surged by 48% in 2025 from the year prior, per new data from BloombergNEF. A total of 112 gigawatts of battery storage capacity was installed worldwide in 2025 — a record high that represents a tenfold increase over the amount constructed in 2021.
So, where are all of these batteries sprouting up? The short answer: mostly in China and the United States.
China alone installed more than half of the world’s grid battery capacity last year. The U.S., meanwhile, accounted for 16%.
Other places are seeing rapid uptake, too. Sun-soaked Australia grew its battery installations by a factor of nearly six last year, albeit from a pretty small base of just 827 megawatts in 2024. The U.K., which shuttered its last coal plant in 2024, saw installations nearly double between 2024 and 2025, to 2.6 GW. Meanwhile, across the broader sub-Saharan Africa region, installations roughly quintupled to 4.3 GW.
Battery installations are now starting to catch up to solar installations, BNEF says. A decade ago, the world was installing 56 MW of solar for every 1 MW of storage. Last year, that ratio was 6-to-1. This year, BNEF expects it to drop to 4-to-1.
The key driver of this growth is the ever-decreasing cost of energy storage, with lithium-ion battery prices dropping by more than 90% over the last 15 years.
The case for batteries is also strengthening as the world builds an incredible amount of wind and solar, since the technology can stockpile wind and solar power when it’s abundant to dispatch later when the grid needs it.
BNEF expects the storage boom to continue as data centers surge onto the grid — especially in the U.S. — and as power demand rises because of the electrification of vehicles and buildings.
The firm forecasts that the world will install a total of 158 GW of batteries in 2026, resulting in 41% year-over-year growth. Although the pace tapers off a bit from there through 2030, BNEF projects that by the end of the decade, annual additions will top 200 GW — more than double the record-setting amount seen last year.
Distributed solar developers say they could build gigawatts of projects to help ease the state’s power crunch — if lawmakers and regulators set clear rules.
Pennsylvania needs more energy. Data centers are pushing demand skyward, utilities can’t build new capacity fast enough, and electric bills are on the rise. Medium-sized solar installations — smaller than utility-scale farms but larger than home rooftop arrays — could help ease the pressure.
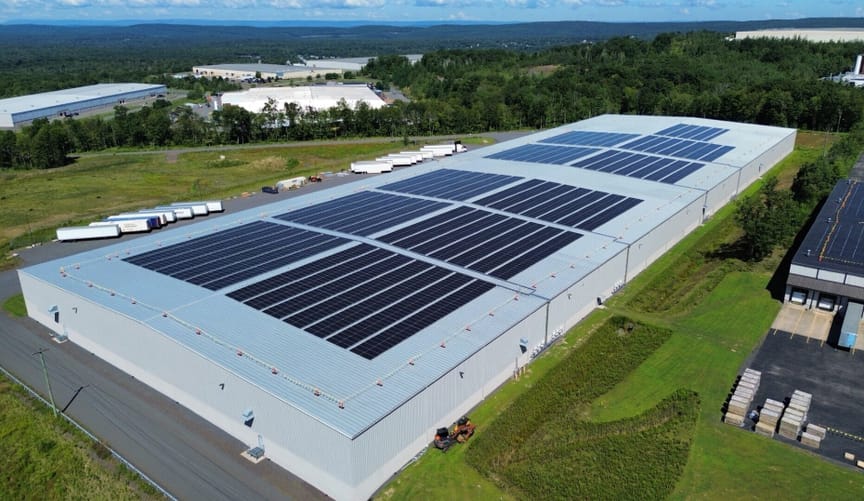
But state lawmakers, utilities, regulators, and solar developers are tussling over the rules that govern such installations, and it’s unclear whether new legislation to resolve their disputes will be passed this year. That worries Victoria Stulgis, president of Black Bear Energy.
Last month, her company and its partners celebrated the energization of 4.9 megawatts of solar on the roofs of two warehouses owned by EQT Real Estate in Mountain Top, Pennsylvania. The two projects, developed by Sigma Renewables and Scale Microgrids and managed by Black Bear Energy, are among roughly 2,100 mid-sized generation projects being planned in the state, most of them distributed solar.
What makes these projects possible is Pennsylvania’s Alternative Energy Portfolio Standards Act, a 2004 law allowing medium-sized projects that generate power with a range of technologies, from solar and wind to waste biomass and coal-bed methane, to earn a relatively high rate for the energy they feed to the grid.
After years of battling with utilities, solar developers won a 2021 decision from the Pennsylvania Supreme Court that laid the groundwork for a rapid expansion of mid-sized projects throughout the state.
But in the past few years, Pennsylvania utilities have cast a pall over that growth with a series of actions that could curtail the revenues these projects can earn, Stulgis said.
“Developers and institutional property owners have invested significant time and capital to develop these solar projects,” she said. Black Bear Energy has completed 15 megawatts of projects, has 22 more megawatts under construction, and has secured interconnection rights for another 106 megawatts across 34 projects, she said.
“Changing those rules midstream would undermine confidence and create real risk for projects already in development,” she said. “Some developers are still leaning in, believing there may be a viable path forward, while others are walking away from shovel-ready projects because of the uncertainty.”
Unlike neighboring states such as Maryland, New Jersey, and New York, Pennsylvania hasn’t adopted a program to enable community solar. Such projects are designed to provide enough revenue to spur third-party developers to build mid-sized solar arrays, to which utility customers can subscribe to lower their bills.
Instead, solar projects of up to 3 megawatts in Pennsylvania are compensated through net metering, a system that’s more commonly used with residential rooftop solar and other small-scale installations. The projects earn a close-to-retail rate for power they send to the grid, notably more than the wholesale rate that larger projects earn.
Solar developers argue that the existing rules allow businesses, school districts, public agencies, and farms to offset rapidly rising electricity costs by hosting solar projects. But utilities argue that paying close to retail rates for electricity from these arrays forces them to raise rates on the rest of their customer base — a version of the cost-shift argument that has dogged battles over rooftop solar net-metering programs over the past two decades.
The Pennsylvania Public Utilities Commission supports the utilities’ cost-shift argument. In March testimony before the state’s House Energy Committee, PUC Chair Stephen DeFrank said that costs from distributed generation projects moving through the interconnection process are projected to exceed $90 million per year by 2027, and could reach $700 million per year if the more than 2,100 projects seeking to be built “proceed under existing rules.”
If utilities aren’t able to recover those costs, they’ll have to increase other rates, he said. Those increases will be “first borne by commercial and industrial customers, including small businesses operating on narrow margins,” he said.
Advocates of distributed solar are pushing back against this cost-shift argument. Rather than increasing everyone’s utility bills, distributed solar will lower utility costs at large, they say, by bringing much-needed new clean generation to a state facing increasing electricity costs driven by the data center boom.
Those are the findings of an April report by Aurora Energy Research commissioned by community-solar developer Dimension Energy. The report analyzed whether building 2 gigawatts of distributed solar by 2030, a number that’s in line with current market growth, would reduce demand for power across the low-voltage distribution grids they’re connected to.
Aurora found that additional solar power could generate a total savings of $1.7 billion over the next 20 years, compared with a scenario under which it wasn’t built. Utilities would still need to pay those projects about $780 million over that time. But that would leave just under $1 billion in net savings that could be applied toward lowering utility customers’ energy bills.
“There are multiple mechanisms by which distributed solar can reduce costs,” said Zachary Edelen, a senior associate at Aurora.
For example, there is the roughly $1.2 billion over 20 years that Pennsylvania utilities could save in decreasing “capacity procurement obligations,” the costs they pay for resources to keep the grid running when demand for electricity peaks, he said. That change could make a substantial difference in Pennsylvania, which is part of PJM Interconnection, the grid operator serving 13 states and Washington, D.C.
PJM’s skyrocketing capacity costs have been a major factor in pushing up utility rates between 12% and 26% for customers of the state’s major utilities from December 2024 to December 2025. That has driven politicians including Pennsylvania Gov. Josh Shapiro (D) to demand reforms from both PJM and the state’s utilities.
Unlike California, Texas, and other states that are awash in solar and need more batteries to store it to lower summertime peak loads as the sun sets, Pennsylvania gets only about 1% of its electricity from solar, Edelen noted. Adding 2 gigawatts would bring that total to about 4% of the state’s total generation capacity.
That means there’s plenty of room for new solar to flow onto utility grids and reduce overall peak loads — especially during the late afternoon summer hours when PJM measures how much peak demand utilities have, and thus how much capacity they’ll need to procure.
These capacity cost reductions are the biggest source of savings from distributed solar, but not the only one, Edelen said. Aurora’s analysis found that 2 gigawatts of distributed solar could cut the cost of purchasing energy from other resources by about $250 million. And because that solar would provide power to nearby customers, it could cut roughly $200 million from future transmission grid expansions that would be needed to deliver power from large power plants farther away. Aurora also estimated that Pennsylvania could earn about $140 million in renewable energy credits from 2 gigawatts of solar.
And that’s not counting the environmental benefits. The state could reduce carbon emissions by more than 11.3 million metric tons and abate harmful air pollution by supplanting fossil-fueled generation with 2 gigawatts of distributed solar.
To be clear, utility-scale solar can deliver electricity at prices well below those being paid to mid-sized projects under the current Alternative Energy Portfolio Standards Act regime. Some energy experts agree with the utilities that policymakers should cut the rates paid to distributed solar systems and instead compensate them at the lower wholesale electricity prices earned by power plants and other competitive generators.
The problem with relying on utility-scale projects is that PJM’s notoriously backlogged interconnection process has made it difficult to add new generation capacity to its grid over the past half decade. PJM recently reopened its interconnection queue after a multiyear pause. But new projects are still expected to take several years to move through that process, and years more to win permits and secure financing to get online.
Distributed solar, by contrast, can be permitted, built, and interconnected to lower-voltage utility grids within a year or two, according to developers working in the region. That could make it one of the few options to prevent what PJM forecasts could be a regional shortfall in energy supplies as early as next summer.
“The reliability of our energy system is increasingly uncertain,” Elowyn Corby, Mid-Atlantic regional director with the nonprofit Vote Solar Action Fund, said in March testimony to the state House Energy Committee. Distributed solar is “one of the fastest, most cost-effective tools available to bring new supply online where it’s needed most, and ease pressure on an overstretched, under-supplied grid.”
Corby also noted that Pennsylvania’s unusual regulatory structure, unlike almost all other net-metering programs in the country, allows distributed solar systems to have little or no “on-site load” — meaning a solar array on a building or one constructed on open land could send all its power to grid instead of using the bulk of it to meet the host’s needs. This makes many of the projects being developed in the state more akin to “merchant” generators that compete with other power producers, lending weight to arguments that they should receive lower compensation.
“Thoughtful reform that addresses how excess generation is treated, and that draws a clear line between distributed generation intended primarily to meet on-site load and merchant generation where the aim is primarily to sell excess generation to the grid, is not an attack on solar — it is responsible stewardship of a valuable policy,” she said.
Pennsylvania lawmakers have proposed similar bills to draw that clear line — one in the Democratic-controlled House and one in the Republican-controlled Senate. Both bills would allow projects that have already been built or that had utility interconnection agreements before mid-2025 to retain existing payment structures, although they would give the Public Utilities Commission the option to cap the total number of projects that qualify.
For projects that don’t meet that cutoff, the bills would significantly cut the rates earned for power sent to the grid. But the bills would offer higher compensation for projects built on “preferred sites,” such as on warehouse rooftops and parking lot canopies, on abandoned mines and capped landfills, and adjacent to closed coal plants, as well as for systems that serve school facilities.
Brandon Smithwood, vice president of policy at community solar developer Dimension Energy, would like to see these kinds of reforms, but he’s not confident that lawmakers will pass a bill. If they don’t, the state will end up with a patchwork of rules. Different utilities around the state have been making changes to how they classify mid-sized projects and lowering the compensation they earn, and developers have been challenging those changes.
Smithwood thinks that solar advocates can reach compromises with individual utilities to preserve some room for the market to grow. He pointed to a settlement agreement reached in March — between utility PPL Electric Utilities, solar trade groups Coalition for Community Solar Access and Solar Energy Industries Association, and the Pennsylvania Office of Small Business Advocate — as a “workable outcome” for solar developers in the absence of legislative action. The settlement would allow up to 140 megawatts of projects to retain retail net-metering compensation for up to 10 years, and then impose a complex and likely lower compensation structure for projects beyond that cap.
But other distributed solar developers are pushing for the legislature’s bills to be passed into law to avoid rules that differ from utility to utility.
“We are asking for regulatory clarity through a legislative foundation with clear and protected rules and rates,” said David Riester, managing partner at Segue Sustainable Infrastructure, a solar and battery project investor. Segue has invested in a portfolio of roughly 250 megawatts of distributed solar projects in development across Pennsylvania, which, if completed, could represent roughly $500 million in infrastructure investment, he said.
That’s just a portion of the total capacity being targeted by developers in the state. “If the light went green tomorrow, I would put the over-under on 700 megawatts getting placed in service within a year, and up to 2 gigawatts by the end of next year,” he said. “There’s this huge supply of power that’s ready to build.”
Segue is considering putting more money into more projects in Pennsylvania, Riester said. But without some clarity from utility regulators or lawmakers on how much these distributed solar projects will be able to earn, “those investments are on hold,” he said.
The much-anticipated stock market debut netted $1.9B for Fervo, indicating strong investor interest in the around-the-clock, carbon-free promise of geothermal.
Fervo Energy, a startup that has pioneered new ways to produce electricity from the earth’s heat, is officially a publicly traded company. It’s the first next-generation geothermal firm to go public.

Today’s initial public offering netted the Houston-based Fervo about $1.9 billion and valued it at roughly $7.7 billion. The company had reportedly sought a much lower valuation of between $2 billion and $3 billion in January but eventually raised its target amid strong investor interest. Fervo secured nearly $2 billion in financing over the course of its nine years as a private firm.
“We are seeing demand grow in a way that we have not seen in the electricity sector in quite a long time,” said Sarah Jewett, Fervo’s senior vice president of strategy. “To come onto the scene at a time when we’re seeing that inflection point of demand, with proven technology… it’s a really welcome time for a story like ours.”
The debut is a major moment for geothermal energy, which can deliver carbon-free power around the clock but has remained a marginal source of electricity worldwide given its serious geological limitations. Fervo makes geothermal energy viable in far more places by harnessing horizontal drilling techniques borrowed from the oil-and-gas industry, for which its CEO and co-founder, Tim Latimer, previously worked.
Fervo’s upsized IPO reflects investor exuberance for any company promising to help meet gargantuan power demand from AI data centers. Fervo has particularly tight ties with Google, which is both an investor in and a customer of the firm. Meta has signed deals with two other advanced geothermal startups in recent years.
“Fervo going public reflects growing confidence in the ability of new geothermal technology to serve soaring electricity demand across the country,” John Coequyt, director of U.S. government affairs at clean energy think tank RMI, said in an email.
Fervo joins longtime geothermal leader Ormat on the public market. Ormat, which completed its IPO in 2004, has been building traditional geothermal power plants in the U.S. and beyond for decades, and it recently began expanding its focus to include “enhanced geothermal systems” like Fervo’s. Ormat saw its stock price climb steadily for years and then nearly double over the last year and change.
Fervo’s IPO comes months ahead of another expected milestone for the startup: the commissioning of its first-of-a-kind power plant in Utah. The development, dubbed Cape Station, broke ground in 2023 and is on track to start sending electricity to the grid in late 2026. A total of 500 megawatts are under construction at the site, but Fervo has the permits in place to quadruple that amount.
Fervo also plans to bring a 115-MW development in Nevada online by 2030, as part of its power purchase agreement with Google and utility NV Energy.
The $1.9 billion Fervo has raised with its IPO will help the company acquire new land and fund general operations — but, Jewett said, “in reality the majority of that money is going to go to project development.”
“We are very, very focused on deploying megawatts — and of course now we say gigawatts,” she said. “The majority of our equity raised today will go to that.”
In its IPO filing, Fervo identified a total of 3.65 gigawatts of power plant capacity that is under construction, ready to be built, or in advanced stages of development. The U.S. currently has roughly 4 GW of installed geothermal capacity.
Fervo’s success will depend on its ability to drive down the cost of the power it produces.
Phase 1 of the Cape Station project is set to deliver power at $7,000 per kilowatt, a price that is competitive with traditional and next-generation nuclear power but far higher than that of natural gas or renewables. Phase 2 of Cape Station, which is also now underway, will deliver power at $5,500 per kW, Jewett said. The company aims to slash that rate to $3,000 per kW.
Fervo has shown some ability to cut costs to date. Between 2022 and 2025, Fervo says it has reduced drilling times by about 75% and slashed per-foot drilling costs by about 70%, marking a significant achievement for the nascent industry. Those trends will need to hold up as the company completes larger-scale installations in the years to come.
Fervo expects to run a loss for “several years,” per its IPO document, as it spends more aggressively to build out its power plants. Its net loss was roughly $57.8 million last year, up from $41.1 million the year prior.
Revenue was a scant $138,000 last year — but Fervo’s IPO document says there is a lot more waiting in the wings. To date, it has signed 658 megawatts’ worth of binding power purchase agreements with major utility Southern California Edison, community choice aggregators, and firms like Google and Shell. That adds up to “approximately $7.2 billion in potential revenue backlog,” per the filing.
It also has an agreement in place with Google, whereby Fervo will give the tech giant the right of first refusal to purchase 3 GW of electricity from certain new projects, though Google itself is under no obligation to say yes. Either party can terminate the deal if no binding commitments have been made by March 2028.
Geothermal energy enjoys more bipartisan support in the U.S. than any other renewable energy source.
While President Donald Trump’s One Big Beautiful Bill Act sunset federal tax credits for solar and wind this July, those for geothermal were left intact. The fracking firm founded and formerly led by Energy Secretary Chris Wright invested in Fervo in 2022. Not one but two bipartisan pro-geothermal bills are under consideration in Congress right now.
And although the Trump administration continues to obstruct wind and solar projects on federal lands, next month the Interior Department is slated to auction off an additional 197,000 acres of land in New Mexico for geothermal energy development.
Maria Gallucci contributed reporting to this piece.
An update was made on May 13, 2026, to include comments from Sarah Jewett, Fervo’s senior vice president of strategy.
The tech giant signed a multiyear contract with Transaera, a startup with MIT roots, for next-gen heat pumps that will help reduce energy costs and emissions.
Amazon has signed a deal for a novel kind of rooftop heat pump that will provide all-electric heating, superefficient cooling, and cheaper energy bills at an undisclosed number of the company’s commercial buildings.
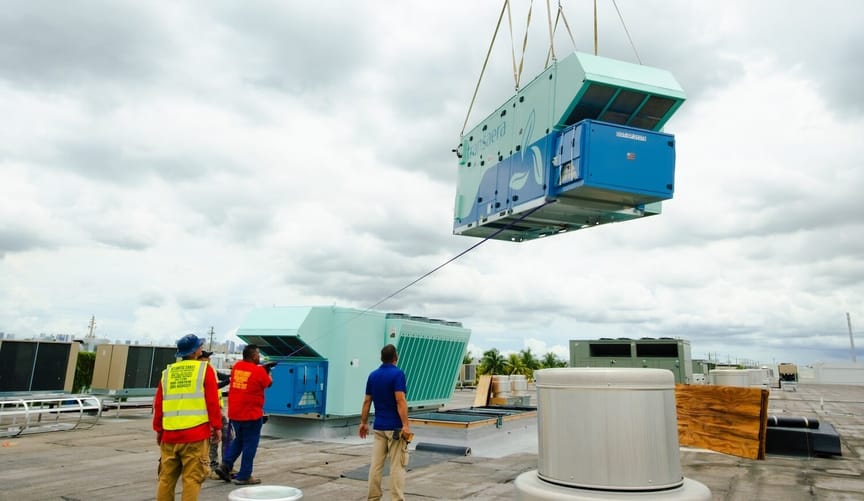
After a successful 6-month field trial at an Amazon logistics facility in hot and humid Houston, the tech behemoth signed a multiyear contract for the specially designed heat pumps with startup Transaera, based in Somerville, Massachusetts. Heat pumps are air conditioners that can work in reverse to provide emissions-free heating, too.
Amazon declined to reveal how many units it has ordered, what it’s paying, and where it would install them, but did say the heat pumps would help the company hit its target of net-zero emissions by 2040.
“At Amazon, we seek technologies that support our Climate Pledge goal,” Asad Jafry, the company’s director of global energy, sustainability, and automation, said in a statement. “This new collaboration supports expanding use of Transaera technology within our global network of buildings.”
Roughly 40% of energy used in U.S. commercial buildings — including big-box stores, schools, grocery shops, offices, hospitals, and hotels — goes to heating and cooling them. Typically performing those functions are packaged heating, ventilation, and air-conditioning units on rooftops. Think big white boxes on flat roofs.
The majority of those units in use today are gas-fired. Even though heat pumps are two to four times as efficient as gas systems, less than 15 percent of the 6 million or so commercial buildings in the country used the electric option in 2024, according to the U.S. Department of Energy.
Two years ago, the agency launched a public-private partnership to bring next-generation heat pumps to market by 2027. Despite the Trump administration’s war on efficiency, the program looks to be on track. And Transaera is one of the participants.
Noah Gabriel, project manager at the decarbonization nonprofit New Buildings Institute, called Amazon’s news “excellent.”
“Awareness of these technologies is still pretty low,” said Gabriel. “Anything that’s expanding from pilot to scaling is going to be really helpful for the market.”
At the Houston facility, Transaera’s tech proved its biggest selling point, according to Sorin Grama, the startup’s CEO and one of its three co-founders, all of whom studied or taught or did both at MIT: Their heat pump can cool buildings using 40% less energy than conventional systems do. The trick? Dehumidifying the air before cooling it.
Warm air “holds” more water than cold air. (Ah, physics.) So ACs naturally provide dehumidification. But conventional systems “typically have to overcool the air” to wring out excess moisture, which drives up energy costs, according to Ankit Kalanki, who leads global initiatives to turbocharge cooling tech for clean energy think tank RMI and has worked with Transaera in the past. (The startup is a member of the tech accelerator program Third Derivative, founded by RMI and the nonprofit New Energy Nexus.)
By midcentury, global demand for air conditioning is expected to nearly triple from 2022 levels, to a staggering 18,000 terawatt-hours, Kalanki noted. That’s more than the entire electricity demand of the U.S., China, India, Germany, and Japan combined.
Transaera’s heat pump could be “a huge game-changer,” Kalanki said. The more efficient electric tech gets, the more easily society can transition to 100% carbon-free energy on fewer solar, wind, and battery plants.
Like other rooftop heat pumps, Transaera’s product costs about 20% more than a conventional unit and has a payback of two to three years, Grama told Canary Media. A whole building equipped with these heat pumps, which last 10 to 15 years, could save millions of dollars over that period, he noted.
Making these efficiency gains possible is a Nobel Prize–winning class of materials: metal-organic frameworks. Under a microscope, they look like clumps of melded sugar cubes. While the material can have thousands of different chemical compositions, Transaera uses a proprietary recipe “that is really good at soaking up water molecules.”
The startup coats a thin layer of this hydrophilic framework on a wheel with a honeycomb structure that air can flow through, Grama explained. As the wheel spins, it sucks moisture from sodden outdoor air before it’s cooled, thus reducing energy use while delivering fresh, conditioned air to improve the health and comfort of a building’s occupants.
Transaera makes the dehumidification portion of the heat pump, and it partners with an unnamed U.S.-based manufacturer that builds the rest of the system. The startup has previously announced $15 million in seed and grant funding. In addition to Amazon, ProFood Properties has installed two Transaera heat pumps at its commercial kitchen in Hialeah, Florida.
Depending on demand, the startup plans to produce hundreds of units per year by 2028. Ultimately, Grama hopes to tailor the tech for individual households, too.
Transaera’s innovation, he said, “applies really well to any size of air conditioner.”
In early March 2026, the European Commission (EC) published a proposal for the Industrial Accelerator Act (IAA),[i] a wide-ranging regulation that would introduce local content and carbon intensity requirements in procurement and other public expenditures, establish a pre-approval regime for large foreign investments in strategic manufacturing sectors, and streamline permitting for industrial decarbonization projects across the European Union. If passed, the IAA would represent the EU’s most ambitious industrial policy since the European Green Deal, reflecting both a commitment to a low-carbon future and intensifying concerns about European competitiveness and supply chain resilience. The draft regulation’s preference for European producers and selected EU trading partners constitutes a softening of Brussels’ position on market neutrality—a shift that reflects a broader defensive turn in EU economic engagement driven by dysfunction in the multilateral trade system and concerns about a surging trade deficit with China.[ii]
This commentary unpacks the IAA’s core provisions, examines its implications for third countries, and identifies the open questions most likely to shape its final form and practical effect.
Relative to other leading economies, the EU has made limited use of fiscal incentives to shape industrial outcomes and structure supply chains since the end of the Cold War. The EU’s state aid rules, World Trade Organization (WTO) commitments, and decentralized allocation of trade, tax, and procurement authority across institutional actors have constrained its ability to pursue broad industrial policies on the scale of the Inflation Reduction Act (IRA) or Made in China 2025.
These constraints have come under increasing pressure in recent years. Russia’s invasion of Ukraine in 2022 exposed Europe’s dependence on imported fossil fuels and sent electricity prices soaring. Concurrent with the energy crisis in Europe, the United States passed the IRA, which authorized immense subsidies to the US energy and transportation sectors, further widening the gap between European and American costs of production.[iii] The crisis also coincided with a dramatic erosion of multilateral trade norms, driven by the United States’ unapologetic use of tariffs.[iv]
This confluence of economic headwinds has fueled anxieties in Europe about the EU’s industrial vitality. In response, EC President Ursula von der Leyen commissioned a report on European competitiveness from former European Central Bank President Mario Draghi.[v] The report, released in 2024, characterized Europe’s stalling economic growth as an “existential challenge” and called for a new industrial strategy based on massive investment and a more strategic use of trade policy to build resilient supply chains, reduce dependencies, and accelerate technological progress. This assessment strengthened an emerging consensus in Brussels that interventionist policies were necessary to secure the continent’s economic future.
The IAA is the EC’s most comprehensive response yet to the Draghi Report. It seeks to leverage some of Brussels’ most powerful economic instruments—procurement, market access, and energy regulation—to direct investment toward strategic sectors and technologies and to ensure that Europe’s energy transition does not undermine its technological innovation and economic resilience.
The IAA’s overarching objective is to strengthen the EU manufacturing sector’s competitiveness and resilience in support of European climate objectives. Specifically, it sets a goal for European manufacturing to account for at least 20 percent of EU GDP by 2035, compared to 14 percent in 2024.[vi] The regulation pursues this goal through four main instruments: local content and greenhouse gas intensity requirements, investment conditionality, permitting reform, and the designation industrial zones.
Local content, emissions intensity, and national security requirements for net-zero technologies and industrial goods
The most commercially significant of these instruments is a set of local content and low-carbon requirements applicable to products containing steel, aluminum, concrete, and mortar intended for use in buildings, infrastructure, and motor vehicles. These requirements would apply to both public procurement (i.e., government purchases, leases, and rentals) of those products and buildings and infrastructure construction projects that receive state support.
To meet the requirements, a specified share of the covered products being procured or used in construction must be “low carbon”[vii] and of “Union origin.”[viii] The IAA defines “low carbon” as goods that meet standards set out in the Ecodesign for Sustainable Products Regulation (2024) and the Construction Products Regulation (2024). It defines “Union origin” to include both European-made goods and those made in countries with which the EU has an FTA or a customs union agreement. In procurement contexts, the category also includes goods from countries that are party to the WTO Agreement on Government Procurement (GPA). The requirements differ by material: steel is subject to a low-carbon threshold, but not to origin conditions; concrete and mortar must meet a 5 percent low-carbon content threshold and be of Union origin; and aluminum must meet a 25 percent Union-origin and low-carbon requirement.
Alongside these new rules for energy-intensive commodities, the IAA includes Union-origin requirements and supply chain deconcentration measures for net-zero technologies. Most notably, the regulation would require that public procurement of electric vehicles (EVs) and consumer subsidies for EVs be limited to Union-origin vehicles. It would also impose Union-origin requirements on procurement of solar, wind, hydrogen, and battery energy storage systems products.
Finally, the IAA would build on the Net-Zero Industrial Act of 2024 (NZIA), which mandates the use of non-price criteria in public procurement and auctions relating to net-zero technologies. These criteria include sustainability and supply chain resilience, with the latter defined to encompass situations where a non-EU country accounts for more than 50 percent of a given technology in the European market. The IAA would further require that at least 40 percent of a member state’s auctions of such technologies meet the NZIA’s resilience and sustainability requirements.
These requirements are not unconditional. Authorities can set them aside where no compliant product is available, where meeting them would cause significant delays, or where the cheapest compliant option is more than 25 percent more expensive than the alternative in procurement or adds more than 30 percent to product costs in support schemes.[ix] Such opt-out thresholds are significant given current market conditions: Chinese producers enjoy structural advantages in sectors such as solar and batteries and the cost differential between Chinese and domestic alternatives is likely to fall within the opt-out band for many covered products.
In addition to these Union-origin and low-carbon provisions, the IAA would introduce a restrictive cybersecurity requirement applicable to certain technologies. For auctions and procurement involving net-zero technologies with control, supervisory control and data acquisition (SCADA), or remote access systems, suppliers identified as “high risk” under the EU’s forthcoming revised Cybersecurity Act are fully excluded.[x] That exclusion applies to 100 percent of relevant auction volume, not just the 40 percent or 8 gigawatt floor that governs the Union-origin requirements.[xi] Unlike the regulation’s Union-origin and low-carbon requirements, there is no cost opt-out available.
The application of these requirements to third-country suppliers depends on both the type of public intervention and the EU’s trade relationship with the supplier’s home country. In public procurement, the GPA[xii] provides a route to equivalence: suppliers from GPA member countries are treated as equivalent to EU producers. However, in renewable energy auctions and support schemes, equivalence is limited to countries that have free trade agreements (FTAs) with the EU.[xiii] This creates a two-tier system: GPA membership provides market access for procurement but not auctions, which account for nearly 60 percent of expected global utility-scale renewable capacity growth through 2030, according to the IEA.[xiv] Additionally, companies manufacturing in an EU-friendly country can still be excluded if they are ultimately owned by entities based in countries without a qualifying agreement.
Investment screening tools
The IAA also introduces a new pre-approval requirement for foreign investments above 100 million euros in sectors where the investor’s home country holds more than 40 percent of global manufacturing capacity.[xv] The proposal identifies four strategic manufacturing sectors: batteries and energy storage systems; electric vehicles; solar technologies; and critical minerals. To gain approval, investors must satisfy at least four of six conditions laid out in Table 1. The framework is designed to ensure that qualifying investments generate meaningful positive spillovers within the EU, rather than maintaining operational and technological capacity with a foreign parent.

Lastly, the regulation addresses two structural constraints on industrial investment that operate before any such commercial conditions arise. A reformed permitting regime, building on procedures originally established under the NZIA, would streamline approvals for a broad range of industrial decarbonization projects, reducing the administrative burden associated with creating and updating national facilities. Member states would also be required to designate an industrial acceleration area within twelve months of the regulation entering into force, with projects inside those zones benefiting from area-level environmental assessments and coordinated infrastructure planning.
The IAA’s investment conditionality regime is framed neutrally and without reference to individual countries. However, the trigger, a 40 percent global manufacturing capacity threshold, currently applies only to China across all four covered sectors.[xvi] Combined with the equivalence architecture described above, China’s position vis-à-vis the IAA is singular: it is neither a GPA party nor an EU FTA partner. As a result, Chinese suppliers face full Union-origin requirements across all intervention types, and Chinese investors face the conditionality regime without any exemptions.
Chinese producers could likewise be adversely affected by the IAA’s proposed amendments to the NZIA’s framework for evaluating tenders in public procurement and auctions. China dominates many of the technologies that would fall within the NZIA’s amended scope. As a result, bidders in European auctions and procurement tenders could face harsher scoring criteria or even disqualification if they propose to sell or deploy covered Chinese technologies.
Unsurprisingly, Chinese officials have voiced strong opposition to these and other aspects of the IAA. China’s Ministry of Commerce (MOFCOM) expressed “serious concerns” and warned it would pursue “countermeasures” if Brussels moves forward with the regulation.[xvii] MOFCOM identified the regulation’s mandatory technology transfers, local content requirements, and equity limits for third-country investors as potentially violating WTO commitments and destabilizing global supply chains, warning that the regulation creates “serious investment barriers and systemic discrimination.”[xviii] In response, EU Trade Commissioner Maroš Šefčovič pledged to “fight tooth and nail for every European job, for every European company, for every open sector.”[xix]
In order to become law, EC proposals must be reviewed and approved by the European Parliament and Council of the European Union, a process that usually results in substantial revisions to draft texts. As the IAA moves through this process, several areas are likely to be the focus of negotiations.
First, the inclusion of FTA and customs union partners and GPA parties in the preference schemes under the IAA may raise concerns that the regulation is insufficiently attuned to the needs and challenges of European industry. The EU has trade agreements with approximately 70 countries covering many of its major trading partners and is actively pursuing FTA negotiations with other large economies. This vast and expanding network may limit the IAA’s effectiveness as a tool to strengthen European competitiveness.
Second, the IAA’s investment conditionality rules may be viewed as too permissive by some European industrial and labor interests. Investor flexibility in meeting three of the five non-mandatory requirements under the regulation could result in an expanded foreign investment footprint in Europe’s industrial sector without substantial technology transfer or supply chain localization—particularly with respect to upstream inputs.
Third, the regulation’s expectation that foreign producers comply with EU standards and reporting requirements to qualify as “low carbon” may aggravate tensions about compliance costs precipitated by other trade and industrial policies such as the Carbon Border Adjustment Mechanism (CBAM) and Regulation on Deforestation-free products (EUDR). Many EU trading partners, particularly developing countries, have criticized the CBAM and EUDR as de facto protectionist, arguing that they condition access to the European market on onerous sustainability standards that are not well aligned with the economic realities of non-European economic and regulatory systems.[xx] For similar reasons, the IAA could be perceived as privileging EU-based firms and those of other advanced economies at the expense of the Global South.
Fourth, the regulation will undoubtedly raise concerns about inflation given current energy prices. Local content and emissions intensity requirements can increase input costs. Although the IAA includes opt-out provisions for situations where Union-origin products would be more expensive, those are set at thresholds that some producers may view as too high. A 20 percent increase in the cost of steel, for example, would not justify the opt-out provisions but could nonetheless significantly raise production costs.
Finally, the regulation’s consistency with multilateral trade norms is likely to face scrutiny. Local content requirements are generally disallowed under WTO rules, including in renewable energy contexts. A key question will be whether auctions to deploy net-zero technologies fall within the scope of the GPA or under exceptions in the Global Agreement on Tariffs and Trade and other WTO agreements. Existing trade jurisprudence does not provide clear guidance on this, and without further clarification the IAA is likely to be contested by one of Brussels’ non-FTA trading partners at the WTO.
The IAA reflects an emerging consensus in Brussels that carbon pricing and emissions standards, which have long been EU officials’ preferred decarbonization tools, may be insufficient to secure European industrial interests in a world where major competitors aggressively deploy fiscal and trade measures. As the IAA moves through the EU legislative process, European leaders will need to decide how much they are willing to intervene in the common market to safeguard the continent’s economic future.
Trevor Sutton, a Senior Research Associate at CGEP, focuses on the intersection of trade, climate, and industrial policy and leads the center’s Program on Trade and the Clean Energy Transition. Trevor previously served as Research Director of the Remaking Global Trade for a Sustainable Future Project and was a co-author of a seminar report on trade system reform, the Villars Framework for a Sustainable Trade System. He has also served in various roles at the Center for American Progress, most recently as a Senior Fellow for Energy and Environment, and the United Nations. Prior to these positions, Trevor served as a judicial clerk on the U.S. Court of Appeals for the District of Columbia Circuit. Trevor has a BA from Stanford University, a JD from Yale Law School, and an MPhil from Oxford University, where he was a Marshall Scholar.
Evelyne Williams is a Research Associate at Center on Global Energy Policy at Columbia University SIPA, where she focuses on the intersection of international trade, energy, and decarbonization. She most recently served as a Foreign Affairs Officer in the U.S. Department of State’s Office of Global Change, where she was the deputy lead negotiator on carbon pricing at the International Maritime Organization (IMO) and represented the United States in international climate negotiations under the UN Framework Convention on Climate Change (UNFCCC) and the Organisation for Economic Co-operation and Development (OECD).
A recipient of the State Department’s Colin Powell Leadership Program fellowship for emerging policy leaders, Evelyne also held roles at the U.S. Mission to the United Nations in New York, the Office of the Geographer and Global Issues, and the Humanitarian Information Unit, where she contributed to socio-economic and climate-related policy initiatives.
Raised in Puerto Rico and the U.S. Virgin Islands, Evelyne has a longstanding interest in island economies, economic policy, and climate resilience. As a student at Columbia, she led a property tax reform and infrastructure resilience initiative in Puerto Rico and collaborated on the development of a graduate course on international monetary policy with Professor Richard Clarida. Earlier in her career, she interned at the U.S. Department of Commerce’s International Trade Administration, supporting export strategies for U.S. firms.
Evelyne holds a Bachelor of Arts in Economics with Distinction from Barnard College, Columbia University, and has pursued a Master of International Affairs at Columbia’s School of International and Public Affairs.
Swad Sathe is a Research Associate at the Center on Global Energy Policy at Columbia University SIPA, where he focuses on researching the nexus between trade and energy. He also provides operational support, including project management and strategic communications, for the Trade and Clean Energy Transition Initiative. He most recently was a Climate Intern at the Niskanen Center in Washington D.C., where he conducted research and wrote articles on permitting reform, transmission expansion, and geothermal energy.
A master’s graduate in International Affairs from the George Washington University, Swad specialized in energy and environmental policy, which culminated in a capstone project on incorporating critical minerals into the USMCA. While in D.C., he also had internships with Observer Research Foundation America, a think tank specializing in U.S. – India relations, and the Climate Leadership Council, a think tank focused on market-based solutions to reduce global emissions.
Swad has a background in fintech, having worked at Sezzle, an alternate payments platform, for over four years. He led Strategic Partnerships at the Minneapolis-based startup, where he forged relationships with over 100 technology and platform partners, expanding the company’s presence in the eCommerce space. He also led CSR efforts, including Sezzle’s B Corp recertification process.
Swad also holds a Bachelor of Science in Economics from the University of Minnesota – Twin-Cities.
[i] European Commission, “Proposal for a Regulation of the European Parliament and of the Council on Establishing a Framework of Measures for Accelerating Industrial Capacity and Decarbonisation in Strategic Sectors (Industrial Accelerator Act),” COM(2026) 100 final, 2026/0068 (COD) (Brussels, March 4, 2026).
[ii] Carlo Martsucelli, “Europe-China Trade Deficit Widens,” Politico Europe, February 13, 2026, https://www.politico.eu/article/europe-china-trade-deficit-widens/;
DRM News, “Macron Warns China Is ‘Destroying European Industry’ without Strong EU Protection,” YouTube video, April 24, 2026, https://www.youtube.com/watch?v=zKTj5999BvY.
[iii] Inflation Reduction Act of 2022, Pub. L. 117-169, 117th Cong., 2nd sess. (August 16, 2022), https://www.congress.gov/bill/117th-congress/house-bill/5376/text; International Energy Agency, Energy Technology Perspectives 2024 (Paris: IEA, 2024), https://www.iea.org/reports/energy-technology-perspectives-2024.
[iv] Casey Crownhart, “China’s Energy Dominance in Three Charts,” MIT Technology Review, July 10, 2025, https://www.technologyreview.com/2025/07/10/1119941/china-energy-dominance-three-charts/; International Energy Agency, Energy Technology Perspectives 2024, chap. 6, https://www.iea.org/reports/energy-technology-perspectives-2024.
[v] Mario Draghi, The Future of European Competitiveness (Brussels: European Commission, September 2024), https://commission.europa.eu/topics/competitiveness/draghi-report_en.
[vi] World Bank, “Manufacturing, Value Added (% of GDP) — European Union,” World Development Indicators, accessed April 2026, https://data.worldbank.org/indicator/NV.IND.MANF.ZS?locations=EU.
[vii] Steel products are subject only to a low-carbon content requirement. The other covered goods are subject to both a low-carbon content and a Union-origin content requirement.
[viii] “Union origin” is a legal term relating to the national source of a product as determined under applicable EU regulations and trade agreements. Somewhat confusingly, it can be defined to include goods that are produced outside the European Union, as is the case under the IAA.
[ix] European Commission, “Proposal for a Regulation of the European Parliament and of the Council on Establishing a Framework of Measures for Accelerating Industrial Capacity and Decarbonisation in Strategic Sectors,” Article 11(3); Ibid., Article 12(3).
[x] Ibid., amended Article 26(1)(a)(iv) and Article 28b of the NZIA.
[xi] Ibid., amended Article 26(7) of the NZIA.
[xii] Office of the United States Trade Representative, “WTO Government Procurement Agreement,” accessed March 2026, https://ustr.gov/issue-areas/government-procurement/wto-government-procurement-agreement.
[xiii] European Commission, “Negotiations and Agreements,” accessed March 27, 2026, https://policy.trade.ec.europa.eu/eu-trade-relationships-country-and-region/negotiations-and-agreements_en.
[xiv] International Energy Agency, Renewables 2025: Executive Summary (Paris: International Energy Agency, 2025), https://www.iea.org/reports/renewables-2025/executive-summary.
[xv] European Commission, “Proposal for a Regulation of the European Parliament and of the Council on Establishing a Framework of Measures for Accelerating Industrial Capacity and Decarbonisation in Strategic Sectors,” Article 17(1).
[xvi] Ibid., Article 17.
[xvii] France24, “China Warns EU over ‘Made in Europe’ Plan, Vows Countermeasures,” April 27, 2026, https://www.france24.com/en/europe/20260427-china-warns-eu-made-in-europe-plan-countermeasures.
[xviii] Huan Zhu, “Beijing Labels EU Industrial Accelerator Act ‘Systemic Discrimination,’” China Trade Monitor, March 10, 2026, https://www.chinatrademonitor.com/beijing-labels-eu-industrial-accelerator-act-systemic-discrimination/.
[xix] Euronews, “EU Vows to Fight ‘Tooth and Nail’ for European Industry as China Threatens Retaliation,” April 30, 2024, https://www.euronews.com/my-europe/2026/04/30/eu-vows-to-fight-tooth-and-nail-for-european-jobs-as-china-threatens-retaliation.
[xx] Olivia Rumble and Andrew Gilder, “SA Calls CBAM ‘Policy Coercive’ and LDCs Call Them ‘Beggar Thy Neighbour’ Instruments,” African Climate Wire, July 24, 2023, https://africanclimatewire.org/2023/07/sa-calls-cbam-policy-coercive-and-ldcs-call-them-beggar-thy-neighbour-instruments/.
Red and blue states alike are working to transform abandoned wells from costly, polluting liabilities into sources of clean power and heat.
As states seek out much-needed supplies of clean, reliable energy, some are looking to an unconventional source: abandoned oil and gas wells harnessed for geothermal heat.
Millions of inactive wells are littered across the United States, the relics of earlier eras of fossil fuel production. A large number of the sites have no official owner, and many are still polluting groundwater and leaking heat-trapping methane. The country has barely scratched the surface in dealing with this problem.
Policymakers in both Republican- and Democratic-led states are exploring whether these sites could instead be converted into new wells for producing geothermal energy. The holes are already drilled in the ground, after all. And regions with widespread oil and gas development have rich subsurface data that geothermal firms need in order to determine where and how to build their carbon-free systems.
The concept is relatively new and largely untested, though scientists and startups are working to change that. States are also laying the groundwork for action by lifting regulatory hurdles and launching in-depth studies.
In Oklahoma, the state Senate is considering a bill that would create a process for companies to buy abandoned oil and gas wells and repurpose them for geothermal energy or underground energy storage. Oklahoma has identified over 20,000 such wells, and state regulators estimate that it would take 235 years and hundreds of millions of dollars to plug all of them. Fixing a single old well can cost anywhere from $75,000 to $150,000 or more, by some calculations, depending on where it’s located and how complicated it is to clean up.
The Well Repurposing Act, which passed Oklahoma’s House in March, is modeled after a similar law that New Mexico adopted last year to address its 2,000-plus orphan wells.
The Oklahoma bill “recognizes that these wells are a liability, and that there may be a way to turn them into some sort of revenue generation and give them value,” said Dave Tragethon, communications director for the nonprofit Well Done Foundation, which works to find and cap abandoned oil and gas wells nationwide. “And if there’s value, that means there’s more of a willingness to address them and more of an opportunity to raise funding.”
In Alabama, legislators passed a law last month that allows the state to approve and regulate the conversion of oil and gas wells to tap alternative energy resources like geothermal. North Dakota adopted a bill last year requiring a legislative council to study the feasibility of using nonproductive wells to generate geothermal power. And in Colorado, state agencies just launched a technical study to evaluate the potential of repurposing old wells for geothermal development and carbon capture and sequestration.
These efforts reflect the growing bipartisan support for geothermal energy, which has largely remained unscathed by the Trump administration’s efforts to block renewable energy projects. The energy resource has the potential to help meet the nation’s soaring energy demand while also slashing planet-warming emissions from electricity and heating.
Geothermal systems work by circulating fluids underground to capture naturally occurring heat, which can then be used to drive turbines for generating electricity or to directly warm the air and water in buildings. The industry is gaining momentum thanks to recent advances in drilling methods and technologies that are making it technically possible or financially viable to access geothermal energy in more places.
Many of those breakthroughs have come from the oil and gas industry, whose skilled workforce of drilling engineers and geoscientists, and deep corporate pockets, have helped launch startups and deploy cutting-edge systems. However, most of that expertise and funding are being poured into building new projects — not figuring out how to retool leaky wells left behind by earlier generations.
“Oil and gas well conversion presents an enormous opportunity, … but it’s pretty far away technologically from being a reality,” said Emily Pope, a geologist and senior fellow at the Center for Climate and Energy Solutions who authored a recent study on next-generation geothermal power.
“There are some hurdles that are still pretty immense,” she said, adding that “it is worth doing some R&D to try and grow.”

One of the biggest challenges is the fact that oil and gas wells tend to reach relatively low to medium underground temperatures. But high heat is key for geothermal projects, especially ones that generate electricity. The hotter the resource, the more energy a developer can wring out of the system.
Plus, fossil fuel wells generally produce smaller volumes of liquid and gas than geothermal wells need in order to spin power turbines or transfer heat to buildings. Geothermal operators might also have to take extra steps to keep nasty elements in the subsurface reservoirs from mixing with the working fluids used to extract heat underground, said Arash Dahi Taleghani, an engineering professor with the Repurposing Center for Energy Transition at Pennsylvania State University.
He added that the high cost of converting wells to geothermal has limited the number of real-world examples so far.
At the University of Oklahoma, however, researchers have been evaluating how to turn four old oil and gas wells into sources of geothermal heat, which they hope to pipe into nearby public schools and homes in the city of Tuttle. The project was awarded a $1.7 million grant from the U.S. Department of Energy’s Wells of Opportunity program in 2022, though it was paused last year during the Trump administration’s sweeping freeze on federal funding and is still waiting to start its next phase, KGOU reported in March.
Saeed Salehi was the Oklahoma project’s director before joining Southern Methodist University as an engineering professor in 2024. He said that repurposing wells for geothermal has several “clear advantages.”
Geothermal firms can avoid significant upfront drilling costs if the wells are already sufficiently deep and hot enough. Oil and gas firms, which today pay millions of dollars to properly seal and shut down modern wells, can give their assets a second life instead. And communities near the aging fossil fuel infrastructure could benefit from having clean, affordable heat and lower winter utility bills.
“We need to collect enough data and have enough successful projects … to take it to scale,” Salehi said, calling repurposed wells “a custom solution for specific regions and areas.”
“Everything is going to take time, but I think we are moving in the right direction,” he added.
A smoother permitting process will be key to speeding things up, something Oklahoma, Alabama, and other states are aiming to address. States have traditionally lacked any regulatory framework for dealing with decades-old wells that no one is technically responsible for. Salehi said it took nearly nine months to get the Tuttle project’s permits, though the process is growing faster now.
In Pennsylvania, Dahi Taleghani said his team is looking to secure funding to repurpose old wells to supply the Penn State campus with geothermal heating. They have also studied the potential for using some of the state’s more than 200,000 abandoned wells to heat agricultural greenhouses, as well as to house energy-storage systems that compress air and stash it underground, acting as low-cost grid batteries.
“Decommissioning wells is expensive, costly, and it’s not generating any revenue,” Dahi Taleghani said. “So we’re looking to [help] create businesses that can go after these leaky wells, fix them, and then use them for geothermal applications.”
AvalonBay saved big and cut pollution by outfitting apartments with tech that runs HVAC equipment more efficiently. Now the firm is scaling the strategy nationwide.
New York City’s biggest buildings face a huge change: By 2050, they must reduce their planet-warming pollution to net-zero, thanks to the metropolis’s Local Law 97. In other words, tens of thousands of structures will need to yank out fossil-fueled systems that heat water and spaces, and replace them with zero-emissions electric versions.

But that doesn’t mean buildings can’t start using their existing natural gas boilers and furnaces more efficiently in the meantime, both to cut utility bills and to comply with Local Law 97’s interim emissions-reduction targets. That’s the approach taken by AvalonBay Communities, one of the country’s largest multifamily real estate investment trusts.
The company partnered with startup Parity in 2022 to install indoor temperature sensors across three of its buildings in Midtown Manhattan, and to hook up the buildings’ heating, ventilation, and air-conditioning controls to a digital platform created by Parity. The software takes in data from the sensors, weather forecasts, and other inputs, and uses it to minimize gas and electricity consumption while ensuring individual apartments don’t get too hot or too cold.
The project cost AvalonBay about $280,000 to implement in the three buildings but has saved more than $540,000 in utility costs so far, according to the companies — more than double its initial targets.
“We blew the projections out of the water,” said Alexander Heckman, AvalonBay’s senior director of engineering. That allowed the firm to break even on its investment in about 16 months.
The company is now rolling out Parity’s tech to all its New York City high-rises, and plans to deploy it across about 4.5 million square feet of its properties on the East Coast, as well as in select West Coast markets, said Freddy Boateng, AvalonBay’s senior manager of sustainability and decarbonization. On Monday, the companies won a 2026 Better Project Award from the U.S. Department of Energy, which recognizes innovative energy-management efforts.
Importantly, while about 40% of the financial savings from the three Midtown buildings came from using electricity more efficiently for summertime air conditioning, 60% came from burning less gas, according to Parity data. That helped cut on-site carbon dioxide pollution by more than 1,000 metric tons so far — a big deal because Local Law 97 requires most buildings over 25,000 square feet to cut emissions 40% by 2030, compared with 2005 levels, in addition to the 2050 net-zero target.
Modulating the operating cycles of fossil-fueled boilers in big apartment buildings isn’t nearly as simple as remote-controlling individual apartments’ air conditioning, Heckman said.
In AvalonBay’s Midtown buildings, both cooling and heating are delivered via packaged terminal air-conditioning units in each apartment. The air conditioning in those wall-mounted boxes can be throttled up and down with the flip of an electrical switch, so to speak. But the heating coils within them are part of a system fed by boilers in the basement and pumps, valves, and other mechanical systems that move steam or hot water throughout the building.
Building managers mess with those systems at their peril. As apartment tenants adjust their preferred heating levels up and down, more steam or hot water is needed to meet those demands. Skimping on burning enough gas at the boiler to provide the temperatures those tenants want when they want them is a recipe for complaints or violations of city regulations.
That’s why almost all central steam and hot-water systems are designed and operated to err on the side of overheating, said James Hannah, Parity’s chief operating officer. The company has seen this over and over in the roughly 100 million square feet of multifamily buildings and hotels in which it has deployed its software across East Coast cities, including New York, Baltimore, Boston, Toronto, and Washington, D.C., and more recently in California and Washington state.
Parity solves this problem by incorporating “weather data for what the temperature is outside and what it’s going to be in the near future, so we can understand what the demand is likely to be in the near future, and optimize the run time of the boiler,” Hannah said. “There’s a lot of room for buildings that have these systems to go from a baseline to the cutting edge of control optimization, which is where we’d like to think we are.”
A prime opportunity is when days veer from chilly to warm. “It might be 20 to 25 degrees one day, and the next day — or even later that day — it might be 45 to 50 degrees. That represents a huge swing in heating demand,” he said.
Most apartments aren’t set up to adjust for those changing weather conditions, he noted. In New York City, the best-known example is older structures with steam radiators that often overheat apartments even on the coldest winter days. But more modern buildings still tend to run their automated HVAC systems on simple schedules that don’t take real-time weather data into account, he said.
Parity is far from the only company using software and data to make building HVAC systems run more efficiently. Dozens of major companies retrofit and manage energy use for governments, schools, universities, and hospitals, which can recoup the cost of efficiency investments over longer periods of time. Meanwhile, companies like BrainBox AI target HVAC optimization for office buildings.
Hannah said that what differentiates Parity from many competitors is its focus on multifamily buildings and hotels, which typically have fewer employees. “In big apartment buildings — and we’re finding similar issues in hotels — you don’t have a big, robust engineering staff like you’d find with a Class A commercial building or a hospital or campus. You can’t go to market with a complex system that requires the on-site team to do a lot of stuff manually,” he said.
Parity’s tech is also helping AvalonBay tap into a new revenue stream: The real estate company is using the software to participate in utility programs that pay customers to turn down power use during times when electricity demand threatens to exceed supply, Hannah said. AvalonBay earned about $30,000 last year by using less electricity for AC during summer heat waves.
Then there are the savings that come from avoiding penalties for failing to meet building performance standards. AvalonBay estimated that using Parity’s software in its three Midtown buildings will help it avoid a potential $290,000 in fines or mitigation costs to comply with Local Law 97. The software could help its buildings comply with similar regulations in Boston, D.C., and other markets.
There’s a lot more room for this kind of optimization. About 40% of the more than 30 million multifamily housing units in the U.S. were heated with fossil fuels as of 2020, according to the Energy Information Administration. But increasing efficiency has its limits: In cities and states that have mandated an end to carbon emissions, those buildings will eventually have to switch to all-electric heating or alternative fuels.
In the late 20th century, a handful of countries — led by Brazil and the United States — turned to liquid biofuels to reduce their dependence on foreign oil markets, producing transport fuels from cheap crops instead.
In the early 2000s, interest in biofuels ramped up sharply, and not just in the Americas. They came to be seen as a leading method to decarbonize road transport. This was because today’s alternative to the combustion engine, the electric car, was still far too expensive.
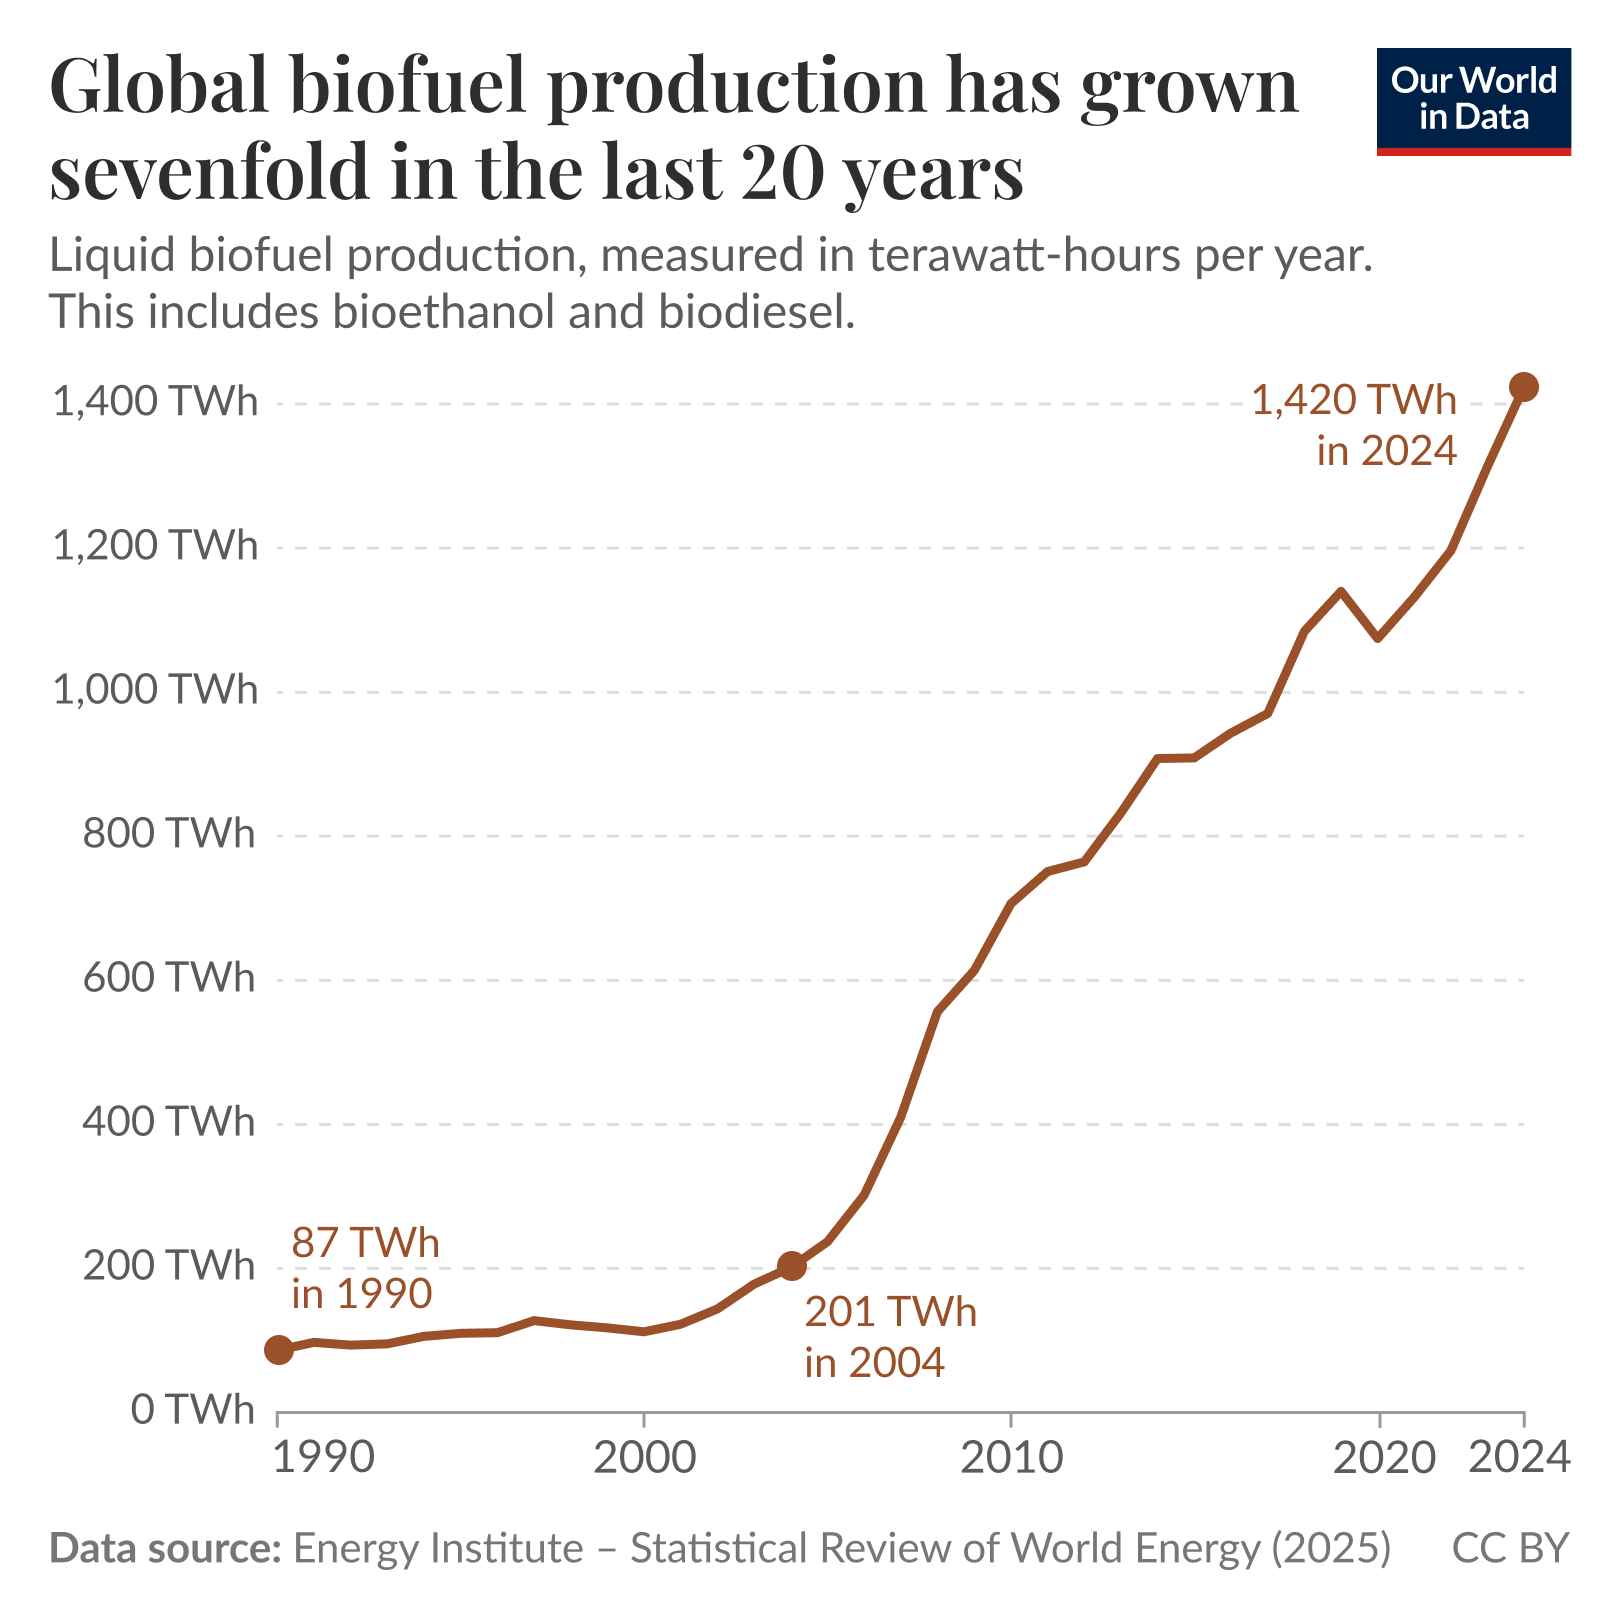
Over the last two decades, global liquid biofuel production has grown sevenfold, as the chart shows.
Electric vehicles are now far cheaper and, in some places, cost-competitive with petrol cars, so biofuels are no longer seen as the central answer to low-carbon transport.
Yet, the world produces more of them than ever, and this is expected to grow over the coming decade, largely due to fuel standards and national policies that have promoted them.


